Talking With Adult Children About Your Estate Plan
A family conversation can introduce the people, documents, and intentions behind an estate plan. You can decide how much financial detail to share and which questions need professional advice.
October 12, 2026
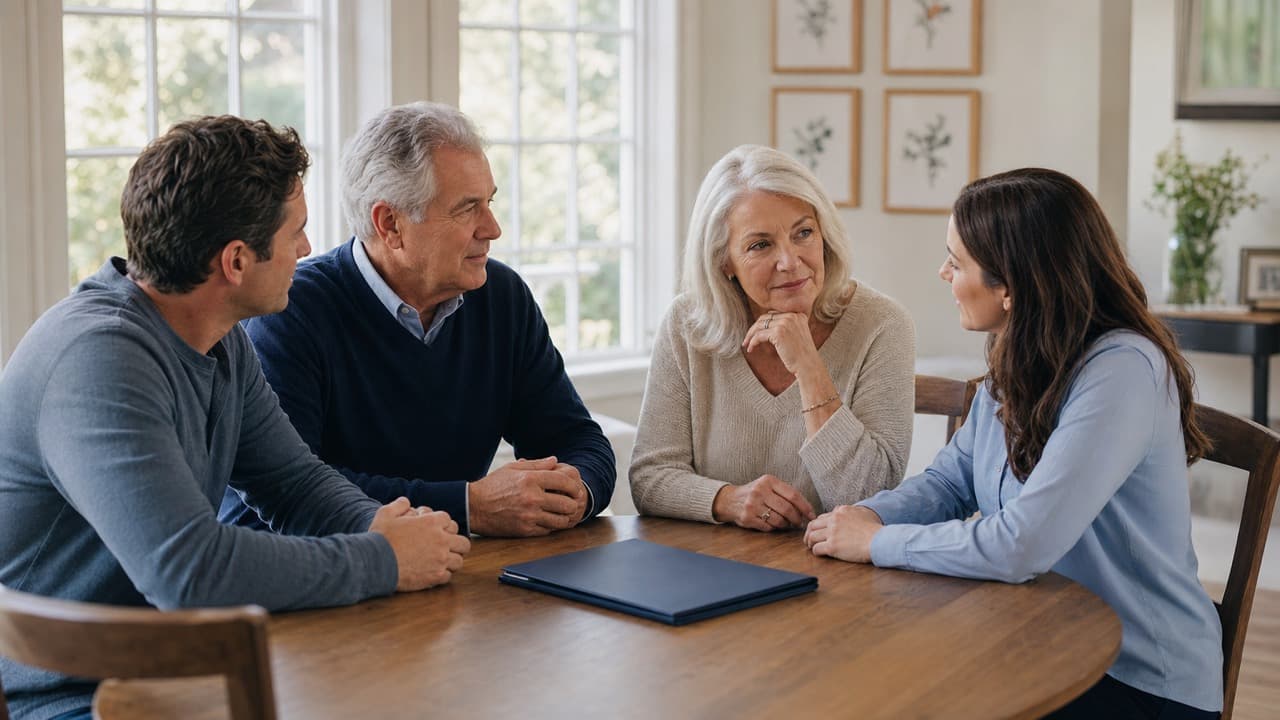
Adult children may know that their parents have an estate plan without knowing who to contact or where the documents are kept. A family conversation gives you an opportunity to explain those practical details while you can answer questions.
You decide what to disclose. A first meeting can focus on intentions and responsibilities without sharing every balance or resolving every family concern.
Decide What the Conversation Should Accomplish
Think about the information your family needs now. A named successor trustee may need to understand the role. Children may need contact details for the attorney and advisor. Family members involved in a business may need to hear how you intend ownership and management to change.
Explain the purpose before the meeting so people can prepare. If a subject is still undecided, say that it remains open. Avoid presenting a tentative preference as a completed legal arrangement.
Consider individual conversations first when a joint meeting could create pressure or expose information someone has asked you to keep private.
Use an Agenda That Fits Your Family
A practical first agenda might include:
- The intentions that matter to you, including care needs or family responsibilities.
- The general arrangement for accounts, property, and any business interest.
- The people named to act and whether they are willing to serve.
- Contact information for your advisor, attorney, and tax preparer.
- Where documents are kept and how authorized people can obtain them.
- Questions to address after the meeting.
Keep financial access secure. Share instructions for lawful access and emergency contacts rather than circulating passwords to everyone attending.
Allow people to ask for an explanation. A term that is familiar to you after years of planning may be new to someone hearing it for the first time.
Discuss Property That Cannot Be Divided Easily
A business or agricultural property can raise questions that a cash account does not. Family members may have different interests in continuing operations, receiving income, or selling.
Discuss those expectations before assuming that equal ownership produces an arrangement everyone can use. Management responsibilities, buyout provisions, and access to cash may need legal and financial planning.
A conversation can identify disagreements, but it cannot guarantee agreement. Your attorney can explain the available structures and their consequences. Avoid making informal promises that conflict with the documents.
Explain That Different Assets Have Different Rules
An inheritance can include property, taxable investments, insurance proceeds, and retirement accounts. Their tax treatment and transfer procedures differ.
Basis is the value used to calculate a taxable gain or loss when an asset is sold. Inherited property often receives a basis adjustment tied to value at death, while lifetime gifts can follow different basis rules. Exceptions matter. Inherited retirement accounts have their own distribution and tax requirements, which depend on the beneficiary and the circumstances.
Family members should know to ask before selling property, moving inherited retirement funds, or signing distribution paperwork. A general conversation about the estate is not a substitute for that transaction-specific advice.
Agree on the Next Practical Steps
Ask the people who will have responsibilities to meet the relevant professionals. Confirm that contact details and document locations are current.
Write down questions that need an answer and who will obtain it. If the conversation reveals a change you want to make, bring it to your attorney or the institution responsible for the beneficiary form.
Revisit the information after a significant family or financial change. There is no need to repeat every detail at each meeting; focus on what has changed and what someone needs to do.
What This Means For You
- Choose the purpose and disclosure level before arranging the meeting.
- Explain responsibilities and confirm willingness to serve.
- Give business and property arrangements enough time for discussion.
- Have proposed changes reflected in the appropriate legal records.
Thiesen Dueker's estate and legacy planning services can help connect financial decisions with your family's intentions. Your advisor can participate alongside your legal and tax professionals when their input would be useful.
If you are considering a family meeting, ask your advisor what information would help everyone prepare.
To speak with Thiesen Dueker, visit thiesendueker.com or call (559) 448-8190.
Frequently Asked Questions
Do I need to share account balances at the first meeting?
No. You can begin with your intentions, key contacts, and where documents are kept. Decide what information is appropriate for your family and the people who will have responsibilities.
Should the advisor or attorney attend?
That depends on the purpose of the meeting. A professional can explain a specific arrangement or help prepare an agenda; a first conversation may also take place within the family.
Does the meeting change the estate plan?
No. A conversation does not replace signed documents, beneficiary forms, or legally effective transfers. Bring proposed changes to the appropriate professional.
Sources
Important Disclosures
Content in this material is for general information only and not intended to provide specific advice or recommendations for any individual.
Securities and advisory services offered through LPL Financial, a registered investment advisor, Member FINRA/SIPC.
This information is not intended to be a substitute for specific individualized legal advice. We suggest that you discuss your specific situation with a qualified legal advisor.
This information is not intended to be a substitute for specific individualized tax advice. We suggest that you discuss your specific tax issues with a qualified tax advisor.
Financial representatives offer access to Trust Services through The Private Trust Company N.A., an affiliate of LPL Financial.
This material was prepared for Thiesen Dueker's use.
Preparing family members for future responsibilities and keeping important family conversations going.
Explore More Topics
Talk With an Advisor
To discuss how this applies to you, call (559) 448-8190.